It wasn’t easier back then. It was different.
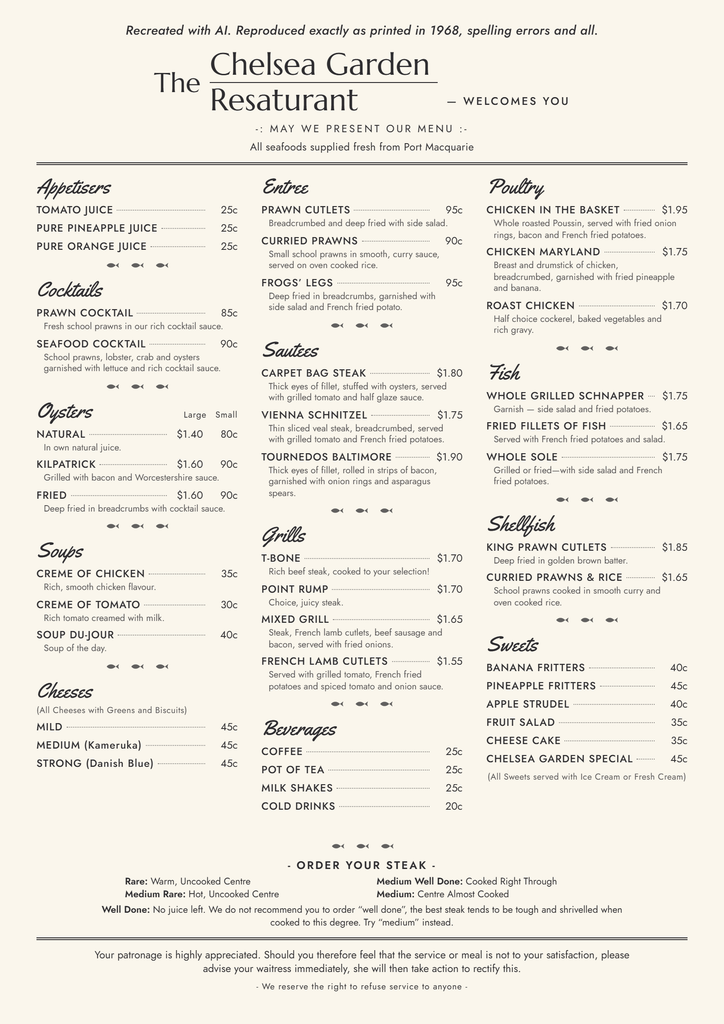
A friend recently sent us a photo of an old menu from the Chelsea Garden Restaurant in Tamworth. A whole grilled snapper was $1.75. Deep-fried prawn cutlets with a side salad were 95 cents. A coffee was 25 cents.
We passed it around the office and had a good laugh, swapping stories from the late 1960s. Then someone said, “Imagine what the kids would say if they saw this.”
I can guess. Something about how easy we had it. If you’ve heard a version of that around your own dinner table, this one’s for you.
Wages were a fraction of what they are now
That snapper looks like a bargain until you remember what people earned. In 1970, the average Australian man earned about $74 a week, and that included his overtime. Today, a full-time adult earns around $2,084 a week before any overtime.
So yes, a meal out cost less. The pay packet was a lot smaller too. Try borrowing for a house on $74 a week. And in regional towns like ours, plenty of people earned well under the national average.
Home loan rates hit 17 per cent
In June 1989, home loan interest rates rose to 17 per cent. A few years later, the early 1990s recession pushed unemployment close to 11 per cent, and almost one in five young people looking for work couldn’t find a job.
I was working in banking around then, and I’ll never forget the conversations with customers who were doing it tough. Many of us remember sitting at the kitchen bench (we called it the ‘breakfast bar’ back then), working out which bills could wait. That kind of memory stays with you. It still shapes how a lot of us think about money.
Compulsory super didn’t exist
When I started work, compulsory super wasn’t part of the picture. The Superannuation Guarantee arrived in 1992 at just 3 or 4 per cent. Today, employers pay 12 per cent of ordinary earnings into super.
That’s one area where our children and grandchildren are well ahead of where we started.
Inflation is hitting young families hard
Here’s where I’ll stick up for the younger generation. If you were born after the early 1990s, you’ve never lived through a long recession, apart from the short, sharp shocks of the global financial crisis and COVID. You grew up with falling interest rates and jobs that were easier to come by.
Then, in the space of a few years, prices jumped. Annual inflation reached 7.8 per cent at the end of 2022, the highest in more than 30 years, and mortgage repayments climbed with interest rates.
Inflation compounds, just like savings do. Compounding works both ways, and with inflation it works against you. That’s why so many young families are feeling the squeeze, even on good incomes.
So no, it wasn’t easier then. Every generation gets its own hard times.
Share what the hard years taught you
Rather than debating who had it tougher, you could pass on what you learnt. A few ideas:
- Start super early. A grandchild’s first job is the perfect time. Even an extra $50 a month, started young, has decades to grow, and if you start young, you barely notice it. MoneySmart’s compound interest calculator shows how much difference time makes.
- Control what you can. Nobody can control interest rates. We can all control what we spend.
- Speak up early when money is tight. If your son or daughter is struggling with their mortgage, the best thing they can do is call their lender’s hardship team sooner rather than later. MoneySmart explains how it works, and the National Debt Helpline (1800 007 007) offers free help from a financial counsellor.
So, when the family gathers next holidays and someone mentions how easy you had it, tell them about the snapper. Then tell them about the 17 per cent.
To find out how we can help secure your financial future, call 02 6583 7588 or book a chat here.